Divorce, Your Home & Your Mortgage: Frequently Asked Questions
Divorce can make even familiar financial decisions suddenly feel overwhelming.
Can I keep the house? Will I qualify on my own? What happens to our mortgage? Where will I live next?
You don't need to have all the answers right now.
That's why we're here.
With more than 20 years of mortgage and financial experience, Jacqueline "Jax" Crider, J.D. helps women navigating divorce understand their mortgage and housing options, ask better questions, and prepare for the financial decisions ahead.
And whenever possible, we encourage you to start these conversations before your divorce is finalized.
Here are answers to some of the questions we hear most often.
Can I buy a house on my own?
Potentially, yes—and don't assume you can't until you've explored your options.
Qualifying for a mortgage on your own depends on factors such as your qualifying income, credit, debts, assets, the proposed terms of your divorce, and the mortgage program you're considering.
If you've relied on two incomes for years—or your spouse traditionally handled the finances—buying a home independently can feel impossible.
It may not be.
And if you aren't ready to qualify today, that doesn't necessarily mean homeownership is off the table. Understanding why you're not ready can help us create a roadmap toward becoming mortgage-ready.
You don't need to know whether you'll qualify before talking to us. That's one of the questions we're here to help you answer.
Can I refinance a buyout from my ex-spouse?
There may be mortgage strategies available when one spouse keeps the marital home and needs to address the other spouse's equity interest, but the details matter—especially in Texas.
Texas has unique laws involving homestead and home equity transactions. How the property, equity, liens, and obligations are addressed during the divorce can affect the mortgage options available afterward.
This is one reason getting a divorce lending and mortgage expert involved before settlement documents are finalized can be so valuable.
Your attorney handles the legal agreement. We can help evaluate how the proposed housing and mortgage strategy may work from the lending side and communicate with your attorney when appropriate.
The earlier the conversation happens, the more opportunity there may be to identify potential complications before they become problems.
Can I use child support or alimony to qualify for a home loan?
Child support or alimony may be usable as qualifying income for a mortgage when applicable lending requirements are met.
Whether it can be used—and how much can be considered—depends on factors including documentation, receipt history when required, expected continuance, the loan program, and your individual circumstances.
This is also why timing can matter during divorce.
Before agreeing to financial terms based on the assumption that certain income will allow you to qualify for a mortgage, talk with a mortgage expert who can evaluate the proposed scenario.
A divorce agreement and mortgage lending guidelines are two different things. Ideally, your strategy should account for both.
Can I afford to keep my current house after divorce?
This might be the most emotionally complicated question we answer.
Your home may represent your children's stability, years of memories, your community, your school district, or simply something familiar while the rest of your life feels anything but familiar.
So it's completely understandable to think:
"I just want to keep the house."
But we need to ask another question:
Will keeping the house support the life you're building next?
That means looking beyond whether you can simply make the mortgage payment.
We may need to consider the mortgage, property taxes, insurance, HOA expenses, maintenance, other debts, income, available assets, equity, future financial goals, and whether refinancing or another mortgage strategy is necessary.
Sometimes keeping the home makes sense.
Sometimes selling creates greater financial freedom.
Our job isn't to tell you which one to choose. It's to help you understand the numbers and your mortgage options so you can make an informed decision.
Can I get my name off the mortgage if my spouse keeps the house?
A divorce decree by itself generally does not remove a borrower from an existing mortgage obligation.
This distinction is incredibly important.
Your divorce agreement may assign responsibility for the home or mortgage to one spouse, but the existing loan is an agreement with the mortgage lender.
Depending on the circumstances and loan, removing a borrower may involve refinancing, an eligible loan assumption or another available solution.
Don't simply assume that giving up ownership of the home means you've also been released from the mortgage.
Ask this question before the divorce is finalized so you understand what needs to happen next.
How We Can Help You Navigate the Home & Mortgage During Divorce
Explore Whether Keeping Your Home Is Realistic
Understand your refinance, affordability, equity, and mortgage options before making a final decision.Plan for Buying a Home During or After Divorce
Explore what you may qualify for, what could affect your timeline, and what steps you can take now to prepare.Understand & Prepare Your Credit
Identify credit issues that could affect your future mortgage options and create a plan for what needs attention.Navigate a Divorce Home Equity Buyout
Understand potential mortgage strategies when one spouse wants to keep the marital home and compensate the other spouse for their share of the equity—including Texas-specific considerations such as owelty liens.Coordinate With Your Divorce Expert Team
When appropriate, we can work alongside your attorney, financial expert, CPA, Realtor, and other trusted experts so the mortgage piece isn't being considered in isolation.Create a Clearer Housing Plan Before the Divorce Is Final
Explore the mortgage implications of your potential decisions early—before you discover that something agreed to on paper is difficult to accomplish in the real world.
You don't need to know which of these you need before talking with us. That's part of what we're here to help you figure out.
What others are saying about us
Christine P., Client
"I appreciate Jacqueline's work this past year. She was great throughout, an invaluable asset, always prepared, and made my quick closing smooth with zero surprises. She ensured care for my ex too with such kindness, which is a challenge. I will pass Jacqueline's name on to anyone needing her services."
Rusty S., Client
"I'm not great with words, but I want to share my experience with Jacqueline. Divorce is never fun and has its fair share of challenges, but Jacqueline answered all my questions, always responded quickly, completed everything timely, and helped me afterwards. I truly appreciated her so much during such a difficult time in my life."
Keith S., Client
"After wasting time with two other mortgage lenders who clearly didn't understand divorce, I was referred to Jacqueline and her team. She not only understood what she was doing, she and her team were so patient with me. Taking time to explain the process, never getting frustrated, and working through my lack of home buying knowledge. This was so refreshing after my prior two experiences!"
Supporting Divorce Attorneys & Financial Experts
The marital home can be one of the most financially and emotionally complicated pieces of a divorce. We help attorneys and other divorce experts understand the mortgage implications surrounding proposed housing strategies—ideally before agreements are finalized.
Services may include:
-Mortgage Scenario & Qualification Analysis
-Marital Home & Refinance Strategy
-Texas Owelty Lien & Home Equity Lending Considerations
-Post-Divorce Homebuying Strategy
-Collaboration With Attorneys & Financial Experts
-Divorce Mortgage Education & Training
-Presentations for Family Law Firms & Professional Groups
-Expert Witness Services, When Appropriate
-Need a mortgage perspective on a client's marital home situation?
Get In Touch
Email: [email protected]
Address
Office:
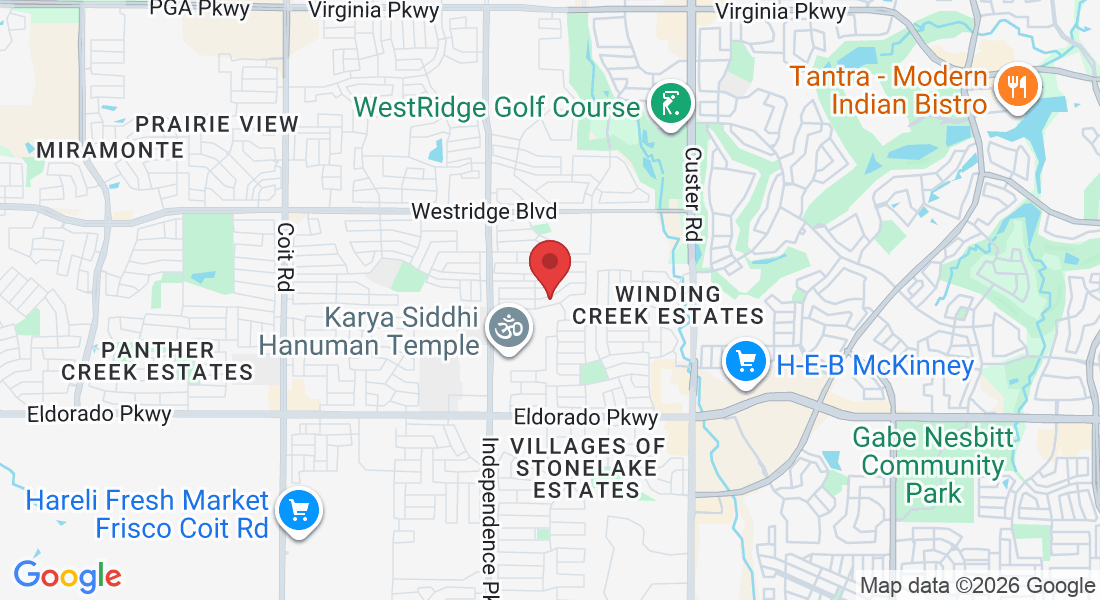
9813 Thomas Jefferson Drive
McKinney, TX 75056
Assistance Hours
Monday – Friday 9:00am – 6:00pm
Saturday- Sunday– By Appointment Only
Phone Number:
469-373-3107
Start Fresh.
WE'RE HERE TO ASSIST - REACH OUT FOR A COMPLIMENTARY CONSULTATION.
PBJ Mortgage NMLS # 2408499